Market overview — definition, scope, and industry significance of Potash Market
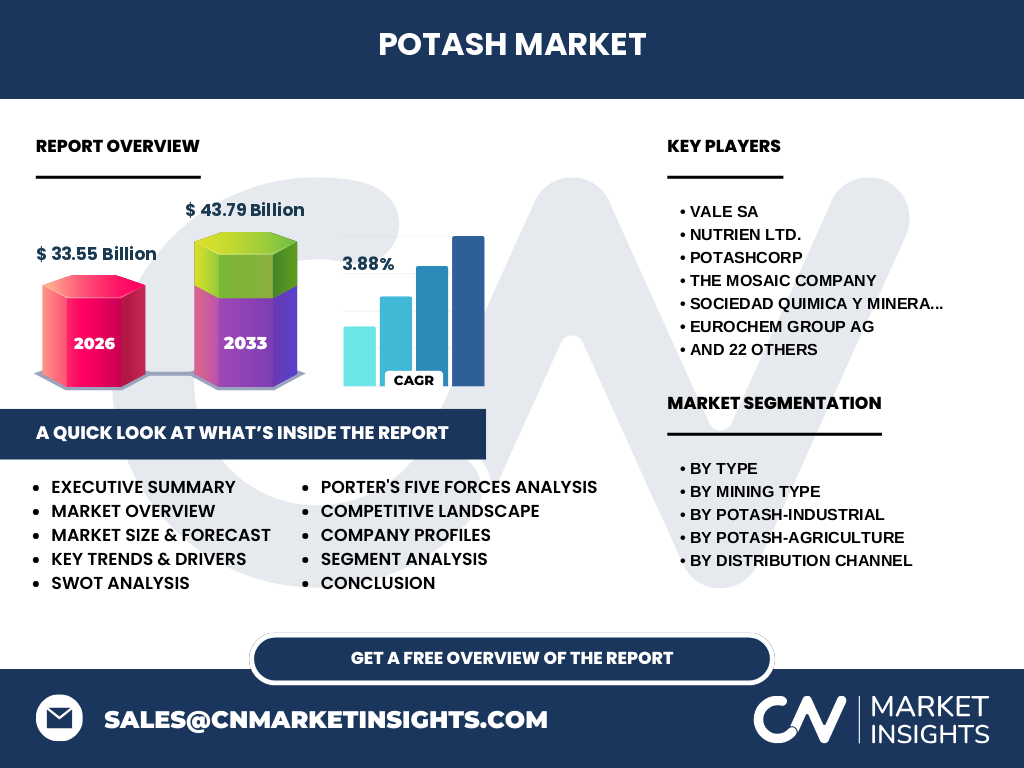
Our analysis indicates that the Potash Market encompasses potassium-bearing minerals and chemicals vital for global agricultural fertilization and industrial manufacturing. Valued at 33.55 Billion in 2026, this sector underpins global food security by supplying essential macronutrients that enhance crop yield, drought resistance, and root development across diverse soil profiles.
Key market drivers, restraints, challenges, and opportunities shaping Potash Market
The primary catalyst remains surging global food demand against shrinking arable land, heavily favoring agricultural applications. However, supply chain bottlenecks, high capital expenditure for underground and surface mining, and stringent environmental regulations act as notable restraints. Opportunities abound in specialized slow-release formulations and expanding industrial processing capabilities.
Emerging trends and growth patterns in Potash Market
The shift toward precision agriculture and sustainable farming practices is revolutionizing consumption patterns. Growers increasingly demand high-purity inputs, boosting the adoption of specialized products like Sulfate Of Potash (SOP) over standard chlorides. Producers are investing heavily in low-carbon extraction technologies to meet tightening ESG compliance standards set by regulatory bodies.
COVID-19 impact analysis — how the pandemic affected Potash Market and the recovery trajectory
Pandemic-era disruptions caused severe logistical bottlenecks, port congestion, and labor shortages across major export hubs in Canada, Russia, and Belarus. Despite initial supply chain shocks, the market demonstrated remarkable resilience. Post-pandemic recovery has been driven by surging crop prices, prompting aggressive restocking by major agricultural cooperatives globally.
Competitive landscape — major players, market concentration, and strategic dynamics
The industry exhibits high consolidation, dominated by major mining conglomerates like Nutrien Ltd., The Mosaic Company, and Uralkali PJSC. These key players leverage massive production capacities and dedicated rail and port infrastructure to control global pricing dynamics. Smaller developers like Gensource Potash Corporation and Highfield Resources Ltd. compete via niche, low-impact extraction techniques.
Executive summary — high-level synthesis of key findings about Potash Market
Driven by rising fertilizer consumption and industrial expansion, our research projects the Potash Market to expand from 33.55 Billion in 2026 to reach 43.79 Billion by 2033, registering a steady CAGR of 3.88%. Strategic consolidation, technological innovation in mining, and localized supply chain resilience define the current investment landscape.
Market forecast — projected growth from 2027 to 2033
Based on our econometric models, the market will scale from its 2026 baseline to 43.79 Billion by 2033, achieving a compound annual growth rate of 3.88%. This trajectory reflects robust volume expansion in emerging economies across Asia-Pacific and Latin America, alongside steady replacement demand in established North American and European agricultural sectors.
Segmentation analysis — break down each segment category, explain what it covers and its market role
By type, the market splits into Potash-Agriculture, dominated by Muriate Of Potash (MOP) and Sulfate Of Potash (SOP), and Potash-Industrial, covering glass production, chemical manufacturing, food processing, and pharmaceuticals. Mining types include underground and surface extraction, while distribution relies on direct sales and retail or e-commerce channels.
Regional market analysis — geographic distribution and performance across regions
Geographically, Asia-Pacific dominates consumption volume due to intensive agricultural practices in China and India. North America remains a powerhouse for both production and consumption, anchored by vast Canadian reserves operated by Nutrien Ltd. and Mosaic. Latin America represents a high-growth frontier driven by extensive soybean and corn acreage expansion in Brazil.
In-depth regional review — detailed examination of key regional markets
North American operations benefit from highly mechanized underground solution mining and robust rail links to major export terminals. In contrast, the Eurasian market, featuring producers like Eurochem Group AG and Uralkali PJSC, navigates complex geopolitical sanctions and alternative logistics routes to supply key buyers in South Asia and Southeast Asia.
Company profiles — strategic positioning of leading companies in Potash Market
Industry giants like Nutrien Ltd. and The Mosaic Company utilize global distribution networks and economies of scale to dominate spot and contract pricing. Meanwhile, specialized innovators such as Sociedad Quimica y Minera de Chile S.A. (SQM) focus on high-margin solar evaporation brines, and IC Potash-focused developers target localized supply security.
Porter's Five Forces analysis — competitive forces assessment
Bargaining power of buyers is moderate to high, tempered by localized crop input demands. Threat of new entrants remains low due to immense capital expenditure barriers and complex mining permits. Rivalry among existing giants is intense, balancing production quotas with global export logistics managed through key maritime ports.
SWOT analysis — strengths, weaknesses, opportunities, and threats
Strengths include essential product necessity and vast reserve endowments among key players. Weaknesses center on high logistics costs and energy-intensive extraction. Opportunities lie in premium water-soluble fertilizers for horticulture. Threats encompass geopolitical trade tariffs, extreme weather events affecting crop yields, and emerging synthetic nutrient substitutes.
Value chain analysis — industry structure and value flow from raw materials to end-users
The value chain originates with raw ore extraction via underground or surface mining methods. Raw minerals undergo beneficiation, crushing, and chemical refining into MOP or SOP. Processed goods move through bulk rail and maritime shipping networks to regional wholesalers, agricultural retailers, and industrial fabricators before reaching end-users.
Investment insights — strategic recommendations and high-potential areas
Investors should prioritize companies integrating sustainable, low-emissions extraction technologies, such as clean energy solution mining. High-potential areas include joint ventures in greenfield projects led by firms like Highfield Resources Ltd. or Gensource Potash Corporation, which offer insulation from traditional high-capex infrastructure vulnerabilities.
Conclusion and key takeaways
The Potash Market offers compelling growth, moving from 33.55 Billion to 43.79 Billion at a 3.88% CAGR. Long-term fundamentals remain exceptionally strong, anchored by global nutritional demands and indispensable industrial uses, making operational efficiency and ESG compliance the ultimate markers of future market leaders.
Research methodology — detail how baseline estimates are triangulated
Our proprietary research triangulates baseline estimates by synthesizing primary stakeholder interviews with mining executives, trade registry import-export statistics from customs databases, and secondary macroeconomic indicators. This multi-tiered cross-verification ensures robust sizing of the 33.55 Billion 2026 baseline and subsequent growth projections.
Scope of the report — coverage parameters and limitations
This report covers global revenue and volume projections for the Potash Market from 2027 to 2033. Limitations include unforeseen macroeconomic trade policy shifts, sudden geopolitical embargoes on major Eastern European exporters, and extreme localized climatic disruptions that could temporarily distort regional agricultural consumption patterns.
Recent developments — company announcements, product launches, partnerships, and strategic moves
Recent industry activity highlights major producers investing in automation and carbon-reduction initiatives. Companies like BHP Group Limited continue advancing their Jansen potash project to secure future supply. Simultaneously, strategic off-take agreements between emerging developers and international trading houses are reshaping traditional supply contracts across key agricultural corridors.